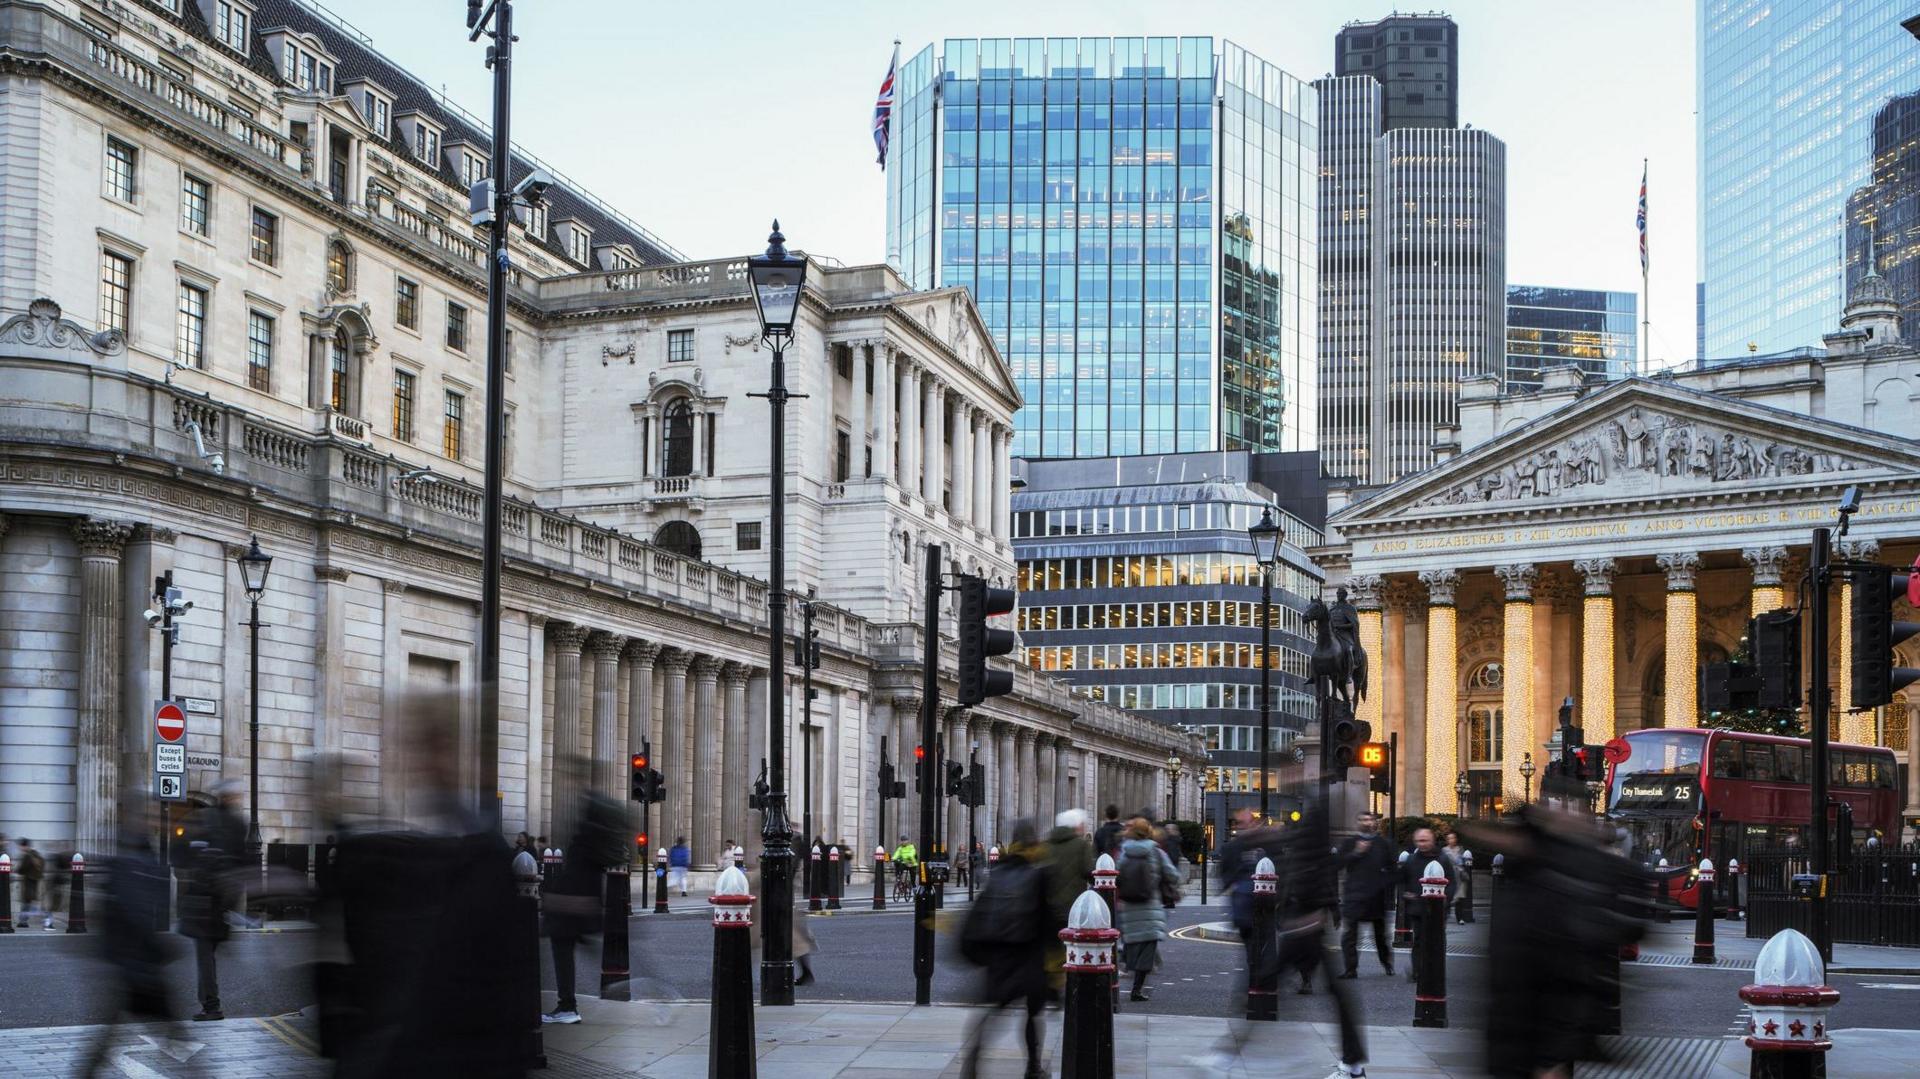
The Bank of England is expected to lift its base rate on Thursday from 3.75% to 4%, which would be the first increase since August 2023. Most analysts see the move as close to certain, and the case for it rests on inflation. The Consumer Prices Index was 3.5% in the year to September 2026, up from 3.1% the previous month and well above the Bank's 2% target. Analysts point to petrol and diesel costs as the main driver, linked to the ongoing impact of the Iran war.
The decision is not a simple yes or no. Chris Cheverall of CMC Markets noted that the debate has shifted to what follows a rise to 4%, because the Bank must balance inflation that remains too high against a growth outlook that has weakened sharply. Holding the rate at 3.75% for six meetings has been defensible, but a quarter-point increase now looks like a reasonable attempt to stop inflation from becoming embedded. Policymakers should be judged on whether they explain the path ahead clearly, not only on Thursday's headline figure.
The household impact is uneven and deserves more attention than the headline gives it. UK Finance calculates that a 0.25 percentage point rise would add £31 a month for someone on a typical tracker mortgage, and about £14 a month for variable-rate borrowers, who must wait for their lender to act. The 510,000 tracker holders and 470,000 variable-rate holders will feel the change first. Fixed-rate borrowers are shielded for now, but lenders have already priced in the expected rise, and anyone coming off a five-year deal faces a far larger bill than they would have paid after a 2021 remortgage.
The comparison with five years ago is stark. Moneyfacts figures show the average five-year fixed rate was 5.99% as of 4 November, against an average of 1.30% for the ten biggest lenders' remortgage deals in the period referenced by broker L&C. Rachel Springall of Moneyfacts is right that choosing a tracker depends on whether a borrower can cope with further rises. Lenders and regulators should make sure that borrowers receive clear, early information about their options before their deals end.
Savers are the obvious beneficiaries, since higher base rates should eventually lift the returns banks offer. That gain is welcome, but it should not be treated as compensation for the pressure households already face. The Bank should keep its focus on bringing inflation back to target, and it should say plainly what it expects next. Households, meanwhile, should review their mortgage timing and savings options now rather than waiting for the next announcement.